Publication date: November 9, 2026
Market data and news cutoff: November 8, 2026
Exchange rate basis: USD/TWD spot selling rate of 32.85
Last week, mill price increases spread to more products. This week, prices started to move in different directions by product. China Steel Corporation (CSC) raised its monthly prices again for December, while hot-rolled coil (HRC) distributors are still absorbing November's higher restocking costs. Reported distributor base quotes for domestic H-beams moved up alongside offers for imported material. Rebar went the other way: major mills held their prices, but southern dealers tested lower resale quotes. How far the mill increases carry through depends on whether distributors can move material at the new prices and how many alternatives buyers still have.
A weaker Taiwan dollar increased import bills, even as Asian steel prices did not rise across the board. In China, output of the five major steel products increased this week and apparent consumption fell. Total inventories continued to decline, but more slowly than last week. Standard carbon steel round bar prices also fell further. Imports remain competitive, but lower US dollar offers may deliver smaller savings once converted into Taiwan dollars.
Key indicators and comparison with the previous four weeks
| Indicator | W42 | W43 | W44 | W45 | W46 latest | Change from W45 cutoff |
|---|---|---|---|---|---|---|
| Iron ore (USD/t) | 90.68 | 90.90 | 90.83 | 90.71 | 92.70 | +2.19% |
| Iron ore (CNY/t) | 682.50 | 672.50 | 675.00 | 672.00 | 687.50 | +2.31% |
| Coking coal benchmark (USD/t) | 270.00 | 266.00 | 266.00 | 268.04 | 255.00 | -4.86% |
| US HRC benchmark (USD/t) | 1,316.08 | 1,356.00 | 1,381.00 | 1,429.00 | 1,425.00 | -0.28% |
| International scrap benchmark (USD/t) | 394.50 | 395.00 | 391.50 | 403.00 | 411.00 | +1.99% |
| Rebar/steel benchmark (CNY/t) | 3,099.00 | 3,089.00 | 3,051.00 | 3,035.00 | 3,046.00 | +0.36% |
| Tangshan common billet, ex-works (CNY/t) | 2,950 | 2,950 | 2,920 | 2,890 | 2,880 | -0.35% |
| USD/TWD spot selling rate | 31.94 | 32.42 | 32.62 | 32.63 | 32.85 | +0.22 |
| USD/CNY | 6.69259 | 6.68630 | 6.66948 | 6.65231 | 6.67240 | +0.30% |
The international scrap benchmark is dated November 5; the other commodity benchmarks and USD/CNY are dated November 6. The billet figure is the prevailing ex-works price in Qian'an, Tangshan, on November 8. US HRC and international scrap are reference benchmarks, distinct from the physical transactions discussed below. USD/TWD is the E.SUN Bank spot selling rate retrieved on November 8.
Flat steel | CSC raises December prices again, but HRC distributor quotes lag
On November 5, CSC announced its December monthly prices. Each of the five listed categories rose by NTD 300/t: regular-grade hot-rolled plate and coil, hot-rolled coil for rerolling, regular-grade cold-rolled coil, electrogalvanized steel for building materials, and hot-dip galvanized steel for building materials and prepainting. In W42, CSC announced a NTD 900/t increase for November, and Chung Hung Steel followed in W43. The December pricing extends the upward move, but at a smaller increment.
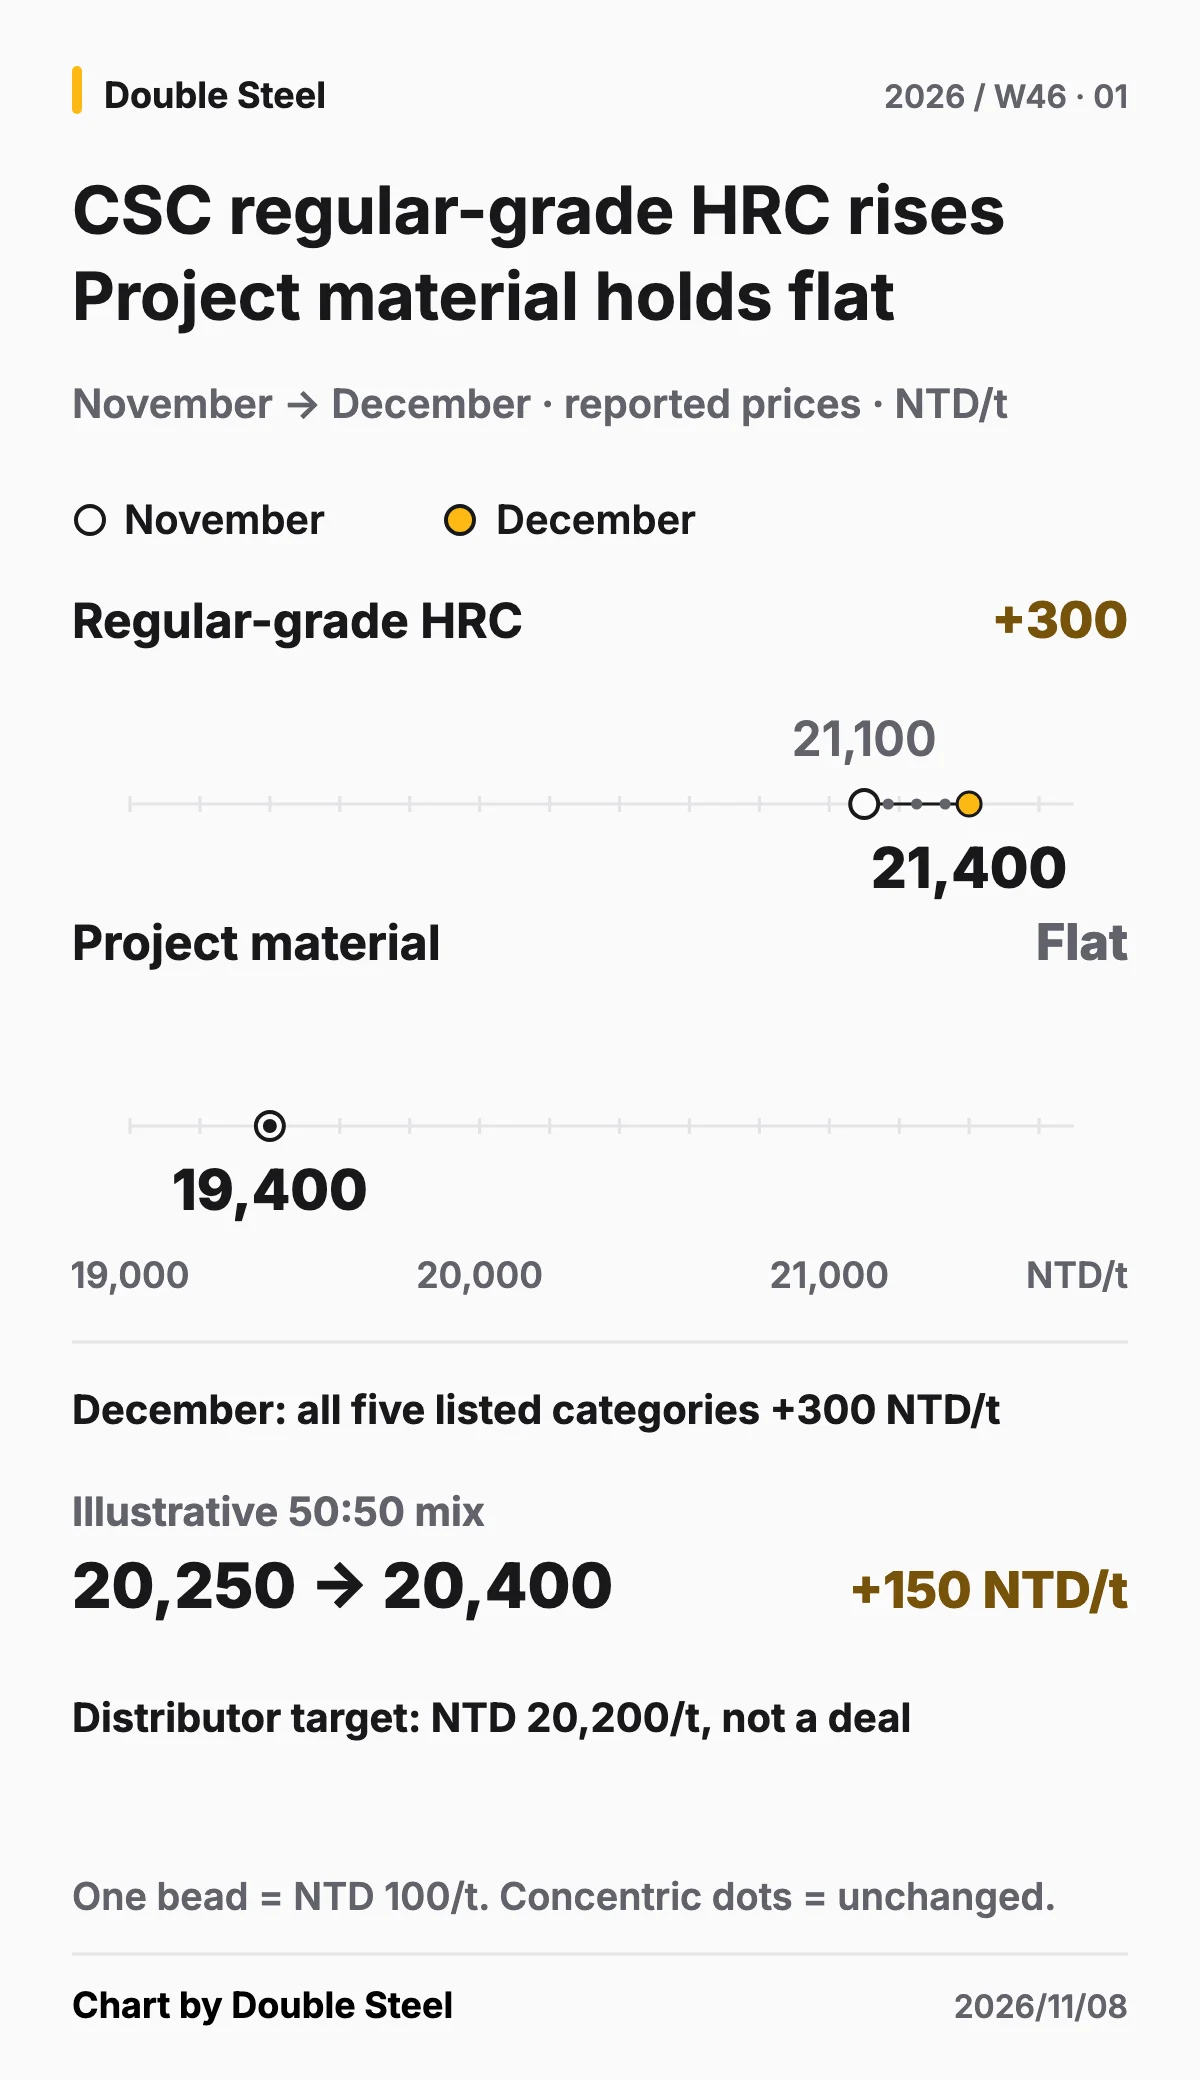
The cost HRC buyers face depends on their material mix. According to market reports, December regular-grade material rose from NTD 21,100 to NTD 21,400/t, while project material held at NTD 19,400/t. At an illustrative 50:50 mix, the average material price rises from NTD 20,250 to NTD 20,400/t, up NTD 150/t. Before the announcement, domestic HRC distributor pickup quotes were still around NTD 19,800–20,000/t, close to the W44 range. The NTD 20,200/t sought by some sellers after the announcement is still a target. Even at that level, quotes would fall short of the illustrative December cost, so the proposed spot increase would not fully absorb the cost of replenishing domestic stock.
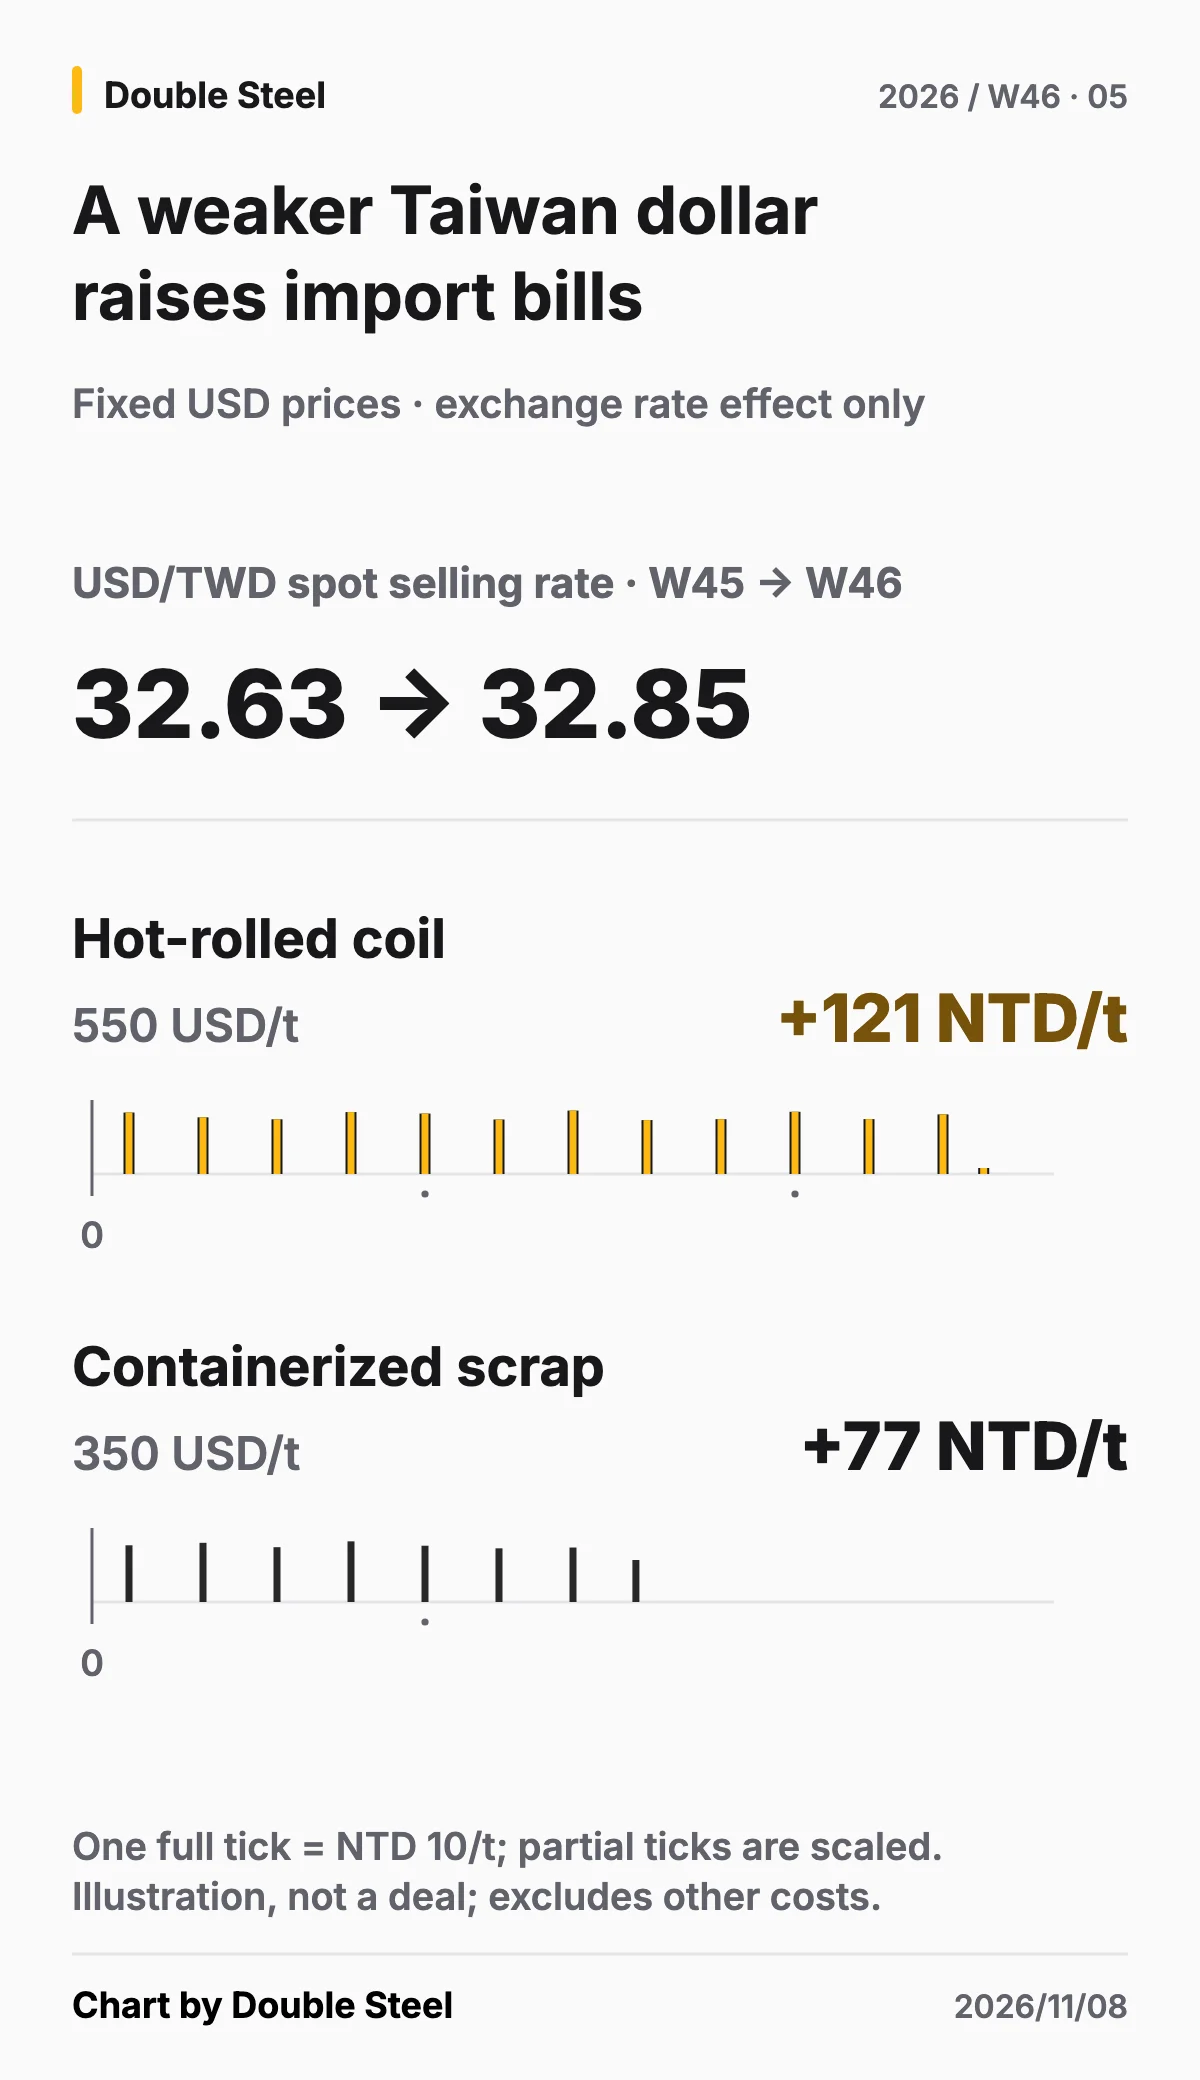
On the import side, dollar offers and currency conversion are pulling in different directions. In W45, POSCO lowered its HRC offer to Taiwan but did not secure a deal. This week, Vietnam's Hoa Phat kept its HRC prices flat in dong, while some dollar equivalents edged up. Formosa Ha Tinh Steel also held its HRC offers flat for January–February delivery. Meanwhile, prevailing SS400 HRC export offers at northern Chinese ports fell USD 6/t on the week to USD 485/t FOB. These regional prices leave buyers room to negotiate. Even so, on the same USD 550/t invoice, the move in the USD/TWD spot selling rate from 32.63 to 32.85 adds NTD 121/t.
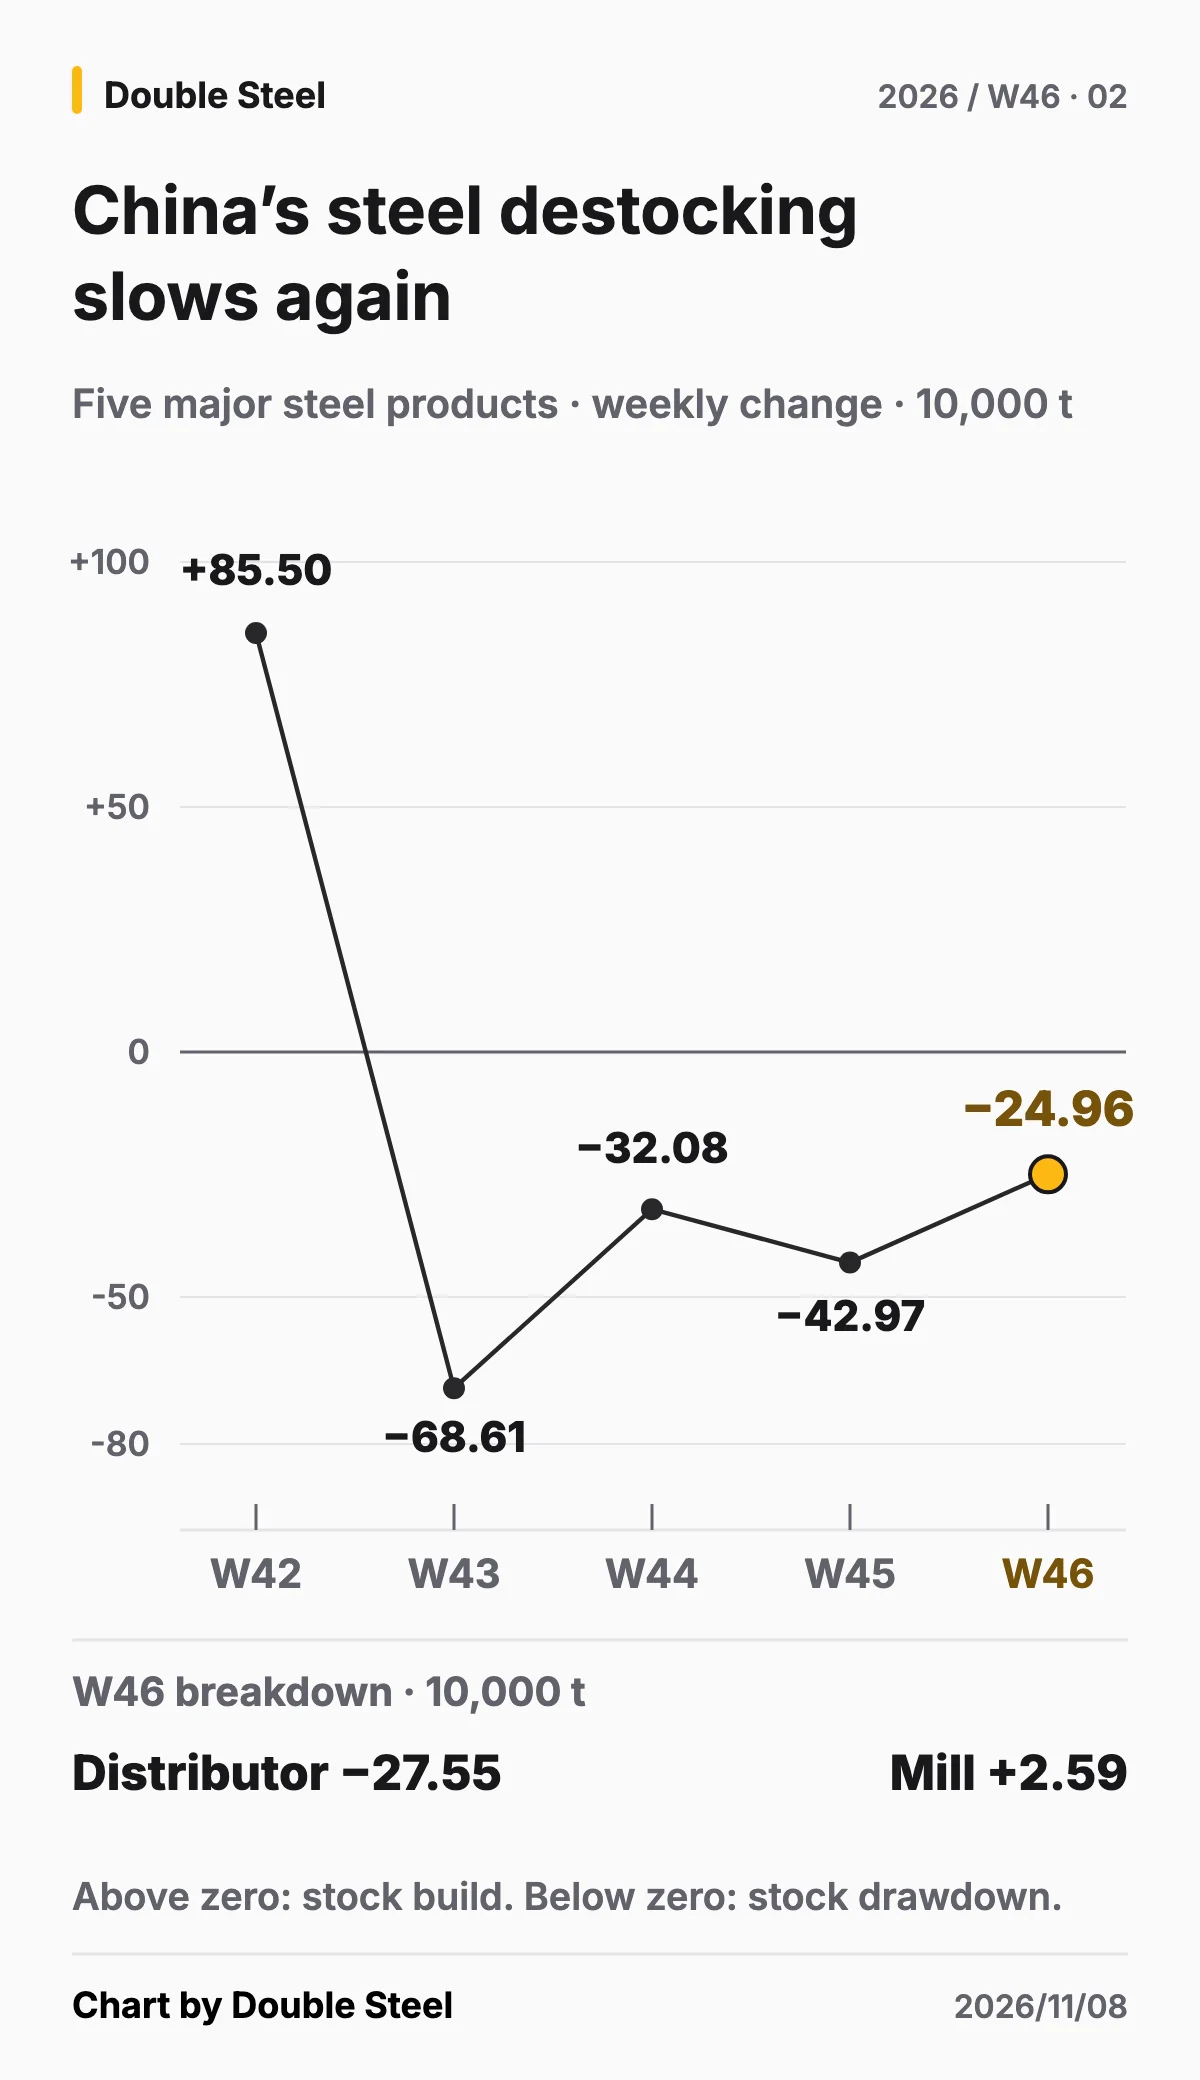
China's flat-steel inventory drawdown accelerated last week, but that support weakened this week. Total inventories of the five major steel products increased by 855,000 t over the W42 holiday, then fell by 686,100 t after work resumed in W43, 320,800 t in W44, and 429,700 t in W45. The W46 drawdown narrowed to 249,600 t. The change went beyond slower destocking: weekly output rose by 70,900 t to 8,048,900 t, apparent consumption fell 1.30% to 8,298,500 t, mill stocks rose by 25,900 t, and distributor stocks fell by 275,500 t. Apparent consumption fell 0.6% for flat steel and 2.6% for construction steel. Separately, at a sample of 37 HRC producers, mill inventories increased by 32,800 t to 710,000 t. Distributor stocks across the five products kept falling, but HRC availability at mills increased, keeping Asian export offers under competitive pressure.
Rebar | Mills hold the new prices as southern dealers test lower quotes
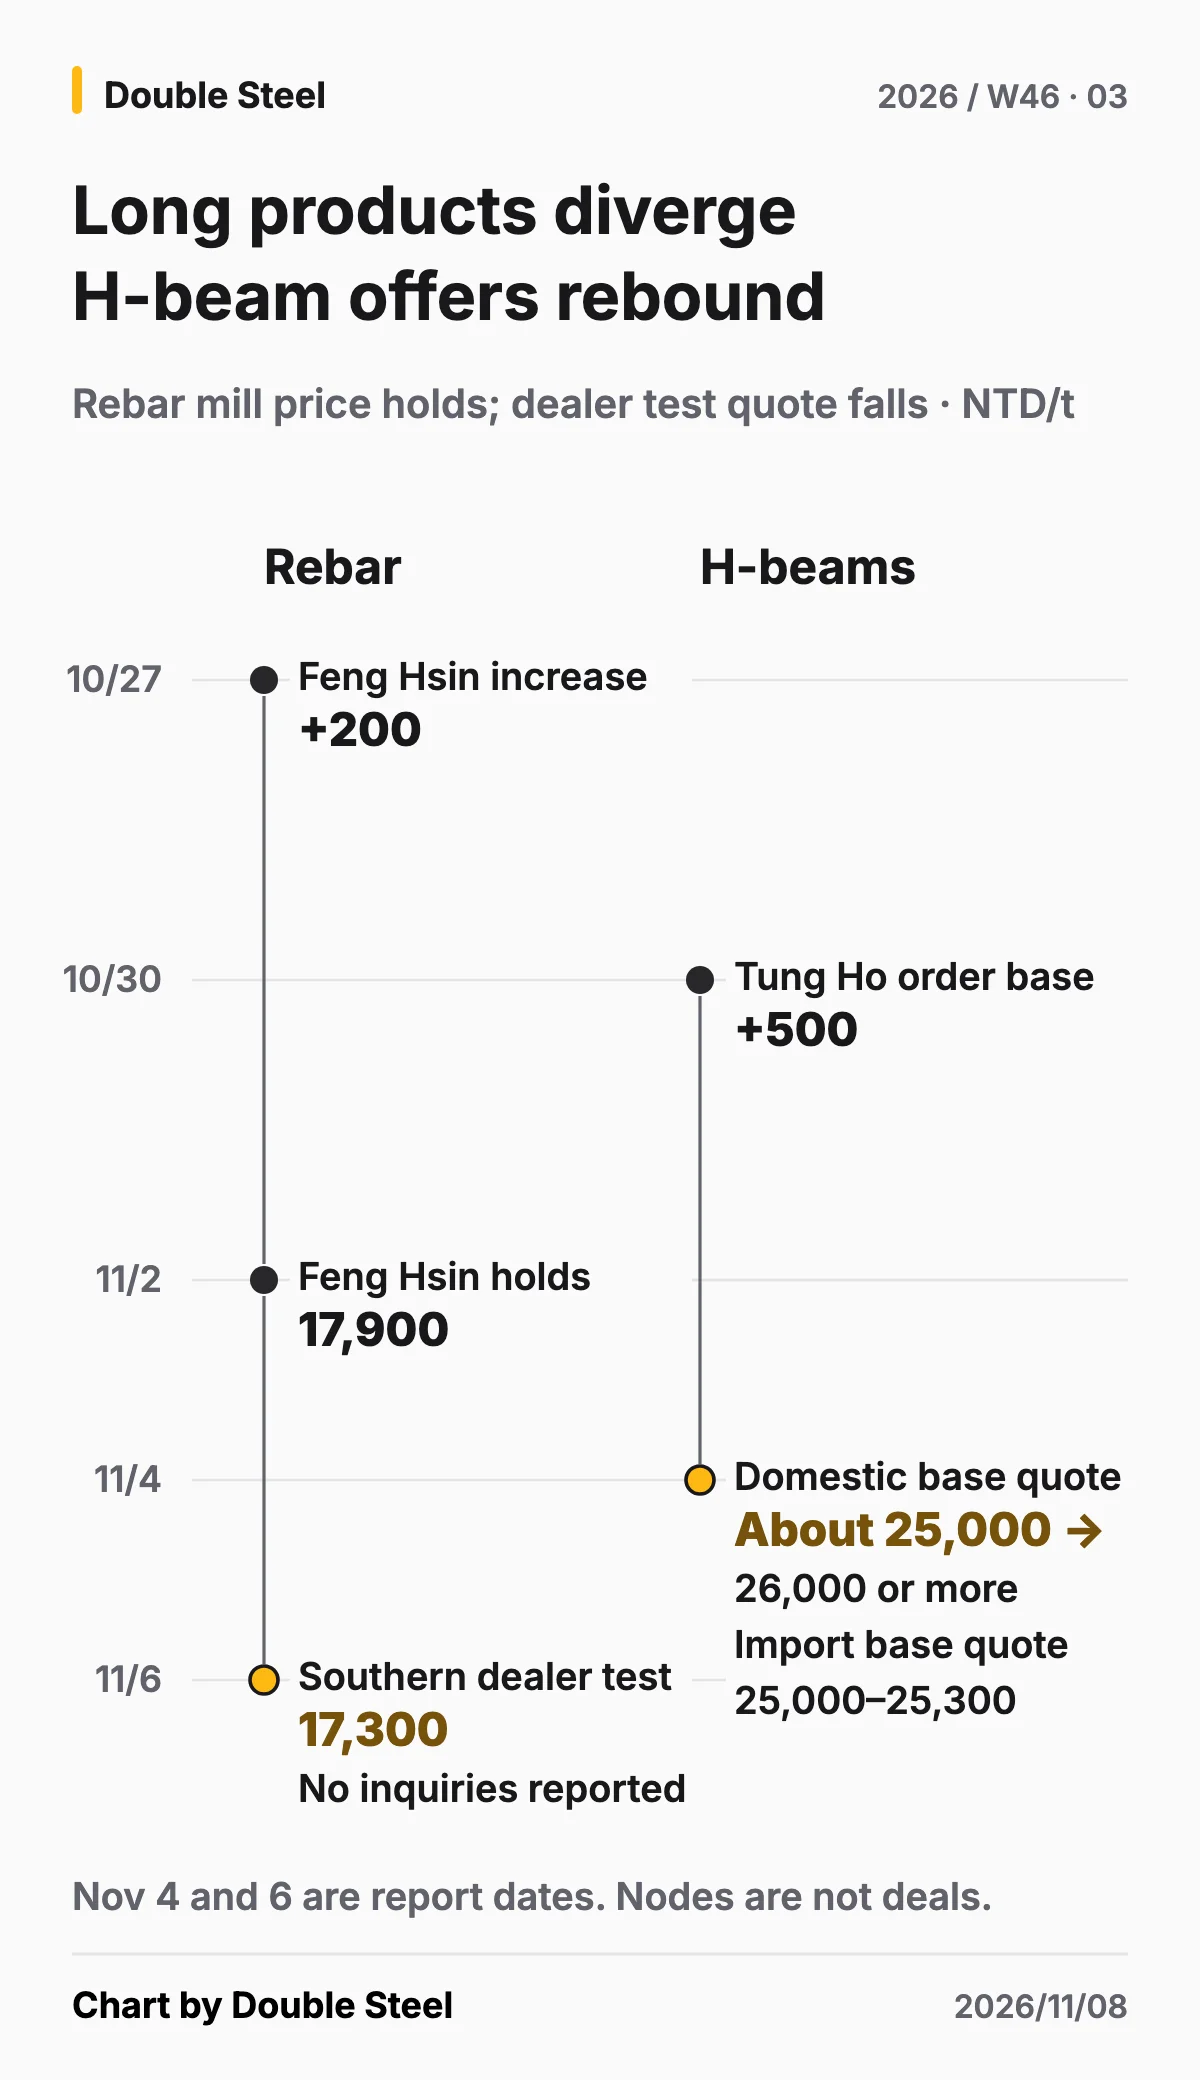
Feng Hsin held prices for rebar, scrap and sections on November 2. Its rebar list price remained NTD 18,500/t, with its mill quote at NTD 17,900/t. Yih Sheng and Ching Hsin Hsin also held their mill quotes at NTD 17,500/t and NTD 17,700/t, respectively. A roughly 6,000 t order was reported in W42, but it did not prompt broader distributor buying at higher prices in W43. In W44, lower prices brought out bulk restocking, and Feng Hsin then raised its price by NTD 200/t in W45.
Dealer test quotes were where prices moved lower. Large southern dealers offered resale material at around NTD 17,400–17,500/t, with one seller testing NTD 17,300/t, below the W45 range of NTD 17,400–17,600/t. Unlike the lower prices that generated bulk restocking in W44, that test quote reportedly did not draw even an inquiry. Mills trying to hold their higher prices still face dealers offering material at lower prices to secure sales.
Sections | H-beam distributor base quotes rebound as import availability becomes key
After Tung Ho's second increase in W43, Dragon Steel raised its H-beam base price by NTD 900/t in W45 and Tung Ho made a third increase of NTD 500/t. Before this week, domestic distributor quotes had struggled to move past around NTD 25,000/t. This week's market reports put imported H-beam distributor base quotes at NTD 25,000–25,300/t, up from about NTD 24,000/t. Domestic base quotes also rose from around NTD 25,000/t to NTD 26,000/t or more. Feng Hsin held its section prices flat this week; the new signal came mainly from H-beam distributors.
Imported material is tight, and domestic mills also have export orders for Australia and the United States. With construction buying still weak, higher import base quotes explain the latest rise in domestic offers better than an increase in local demand. Another mill increase for the domestic market is still market talk. Whether the higher quotes hold depends on whether shipments follow at those levels.
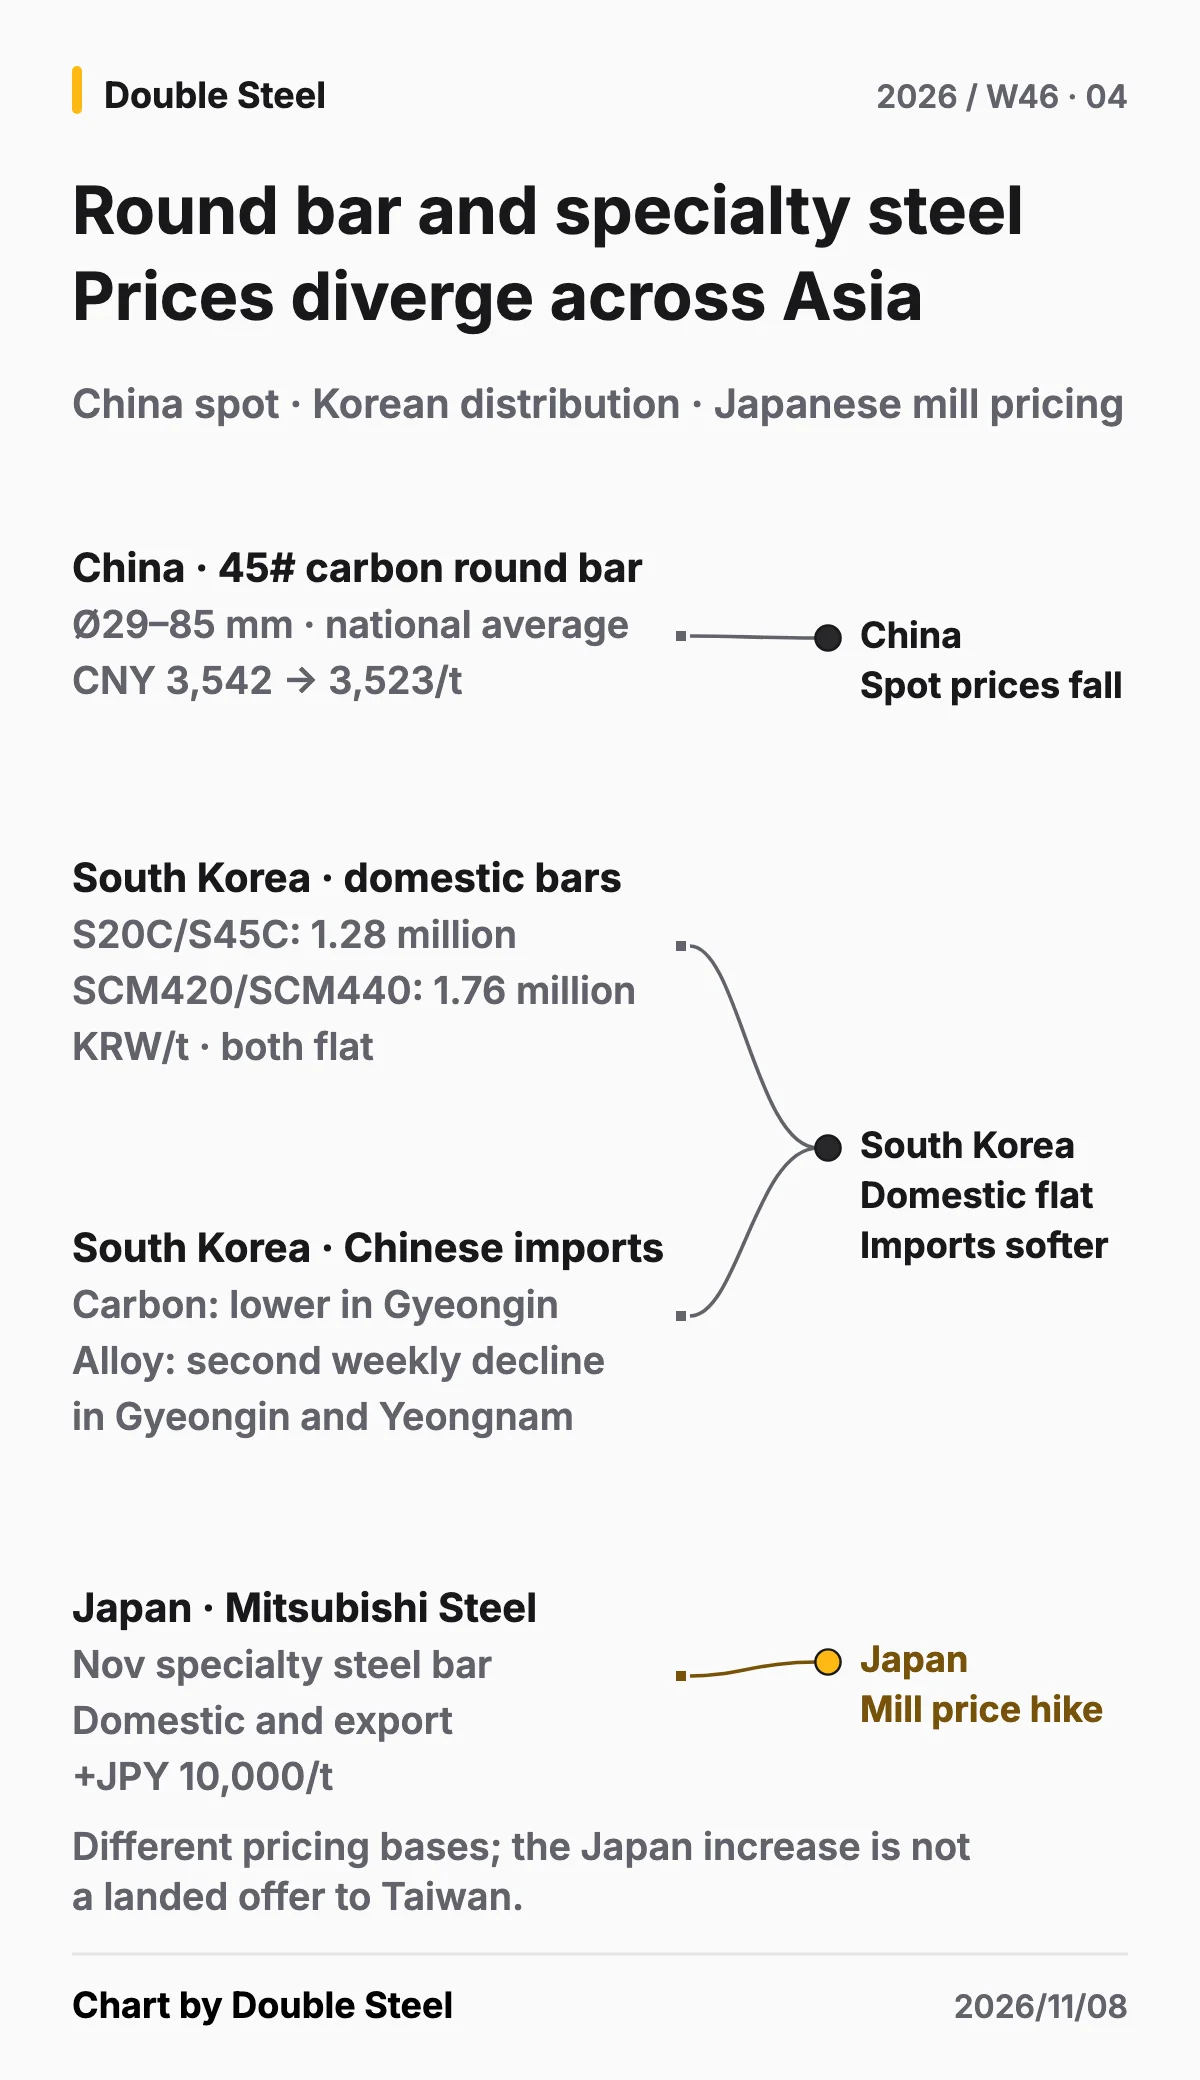
Round bar and specialty steel | China spot prices fall, Korean domestic prices hold, and Japanese mills raise prices
Taiwan had already seen prices diverge by product in recent weeks. In W44, medium-carbon straight bar faced competition from low-priced spot and forward imports. In W45, Feng Hsin raised prices for small sections, lifting base prices for some small-diameter standard-grade round bars. This week's new signals came mainly from China, Japan and South Korea, with the clearest spot pressure in standard carbon steel round bar.
Mysteel's nationwide average for Chinese 45# carbon steel round bar, 29–85 mm in diameter, was CNY 3,523/t on November 6, down CNY 19/t from W45's CNY 3,542/t and below CNY 3,590/t in W42 and CNY 3,580/t in W43. In a survey of East China distributors on the same day, Huaigang's 45# was quoted at CNY 3,460/t and its 40Cr at CNY 3,800/t, both down CNY 30/t from the previous week. Lange Steel's sample of 46 quality and specialty steel mills recorded an inventory increase of 36,100 t to 1,614,100 t, while distributor stocks across 25 cities fell by 26,300 t to 1,318,700 t. In W44, inventories rose at both levels. This week, distributors limited stocks and cut prices to move material, while mill inventories continued to build, weighing on carbon and alloy structural round bar quotes.
In the first week of November, South Korean domestic distributor prices held steady at about KRW 1.28 million/t for S20C/S45C round bar and KRW 1.76 million/t for SCM420/SCM440. In the same market, Chinese-origin carbon steel round bar prices continued to fall in Gyeongin, and Chinese-origin alloy round bar prices fell for a second week in both Gyeongin and Yeongnam. The divergence in Korean distributor quotes shows the price pressure appearing first in imports.
Japan's Nikkan Tekko Shimbun reported that Mitsubishi Steel announced on November 4 a JPY 10,000/t increase from November across all specialty steel bar products for domestic sale and export, citing higher energy, ferroalloy and logistics costs. Following Aichi Steel's contract price adjustment in W45, another Japanese mill has now moved prices higher. Falling Chinese standard round bar prices, diverging domestic and import prices within South Korea, and the Japanese mill increase show how differently each supply market is pricing its material. New landed offers will show whether the Japanese increase reaches Taiwan.
Steelmaking raw materials | Iron ore rebounds, coking coal weakens, and the exchange rate weighs on EAF feedstock purchases
Seaborne iron ore rebounded late in the week. Physical quotes for Australian 62% fines shipped to China rose from USD 92.25/t CFR on October 30 to USD 95.10/t on November 6. Even as ore prices rose, Mysteel's sample of 247 mills showed daily hot metal output falling by 11,800 t to 2,306,900 t. The ore rebound did not coincide with a recovery in blast furnace output.
Metallurgical coal moved differently. The coking coal benchmark fell from the previous cutoff, and on November 6 Mysteel also reported softer forward seaborne coking coal prices, while port offers held up comparatively well. China's spot coke prices have been largely steady since two October reductions. Weaker coal prices and lower hot metal output made mills more willing to press for cuts, but a new round of reductions had not been confirmed as implemented by the cutoff. Higher ore prices and softer support from coal and coke are pulling blast furnace costs in opposite directions.
Overseas and Taiwanese scrap markets also moved differently. Initial reports pointed to higher US domestic scrap prices for November, and a deep-sea US scrap cargo was reported sold to Turkey at USD 407/t CFR. In Taiwan, reported bids for US containerized scrap remained around USD 343–345/t CFR, below the same report's assessed workable range of USD 348–350/t CFR. Even with the dollar price fixed at USD 350/t, this week's exchange rate change adds NTD 77/t to the invoice. With rebar dealers testing lower prices, electric arc furnace mills have less room to take higher-priced imported scrap.
Qian'an common billet in Tangshan recovered from midweek lows but ended the reporting period CNY 10/t below the previous cutoff. Russian EAF billet moved from waiting for offers in W45 to price negotiations. Taiwanese buyers reportedly bid below USD 500/t CFR for high-tensile vanadium-alloyed billet, but the bid was not accepted. For buyers looking to substitute billet for scrap, lowering the bid and securing material for delivery remain two different things.
What to watch next week
- Flat steel: Whether domestic HRC sees sustained transactions above NTD 20,000/t, and whether new import offers widen the savings on alternatives once converted into Taiwan dollars.
- Long products: Whether shipments of like-for-like H-beams go through at the higher base quotes, and whether lower-priced rebar offers in the south bring back bulk buying.
- Round bar and raw materials: Whether Chinese quality and specialty steel mill inventories keep rising, whether new offers reflect Japanese specialty steel increases, and whether firm transaction prices and delivery dates emerge for Russian billet and US scrap.
The clearest change this week was the rise in distributor base quotes for both domestic and imported H-beams. HRC sellers are still testing higher quotes, while southern rebar dealers tested lower ones. A recovery in margins depends on whether products with higher quotes can ship at those prices, and whether the cost of imported feedstock falls to a level finished steel prices can support.
Sources: TradingEconomics (commodity benchmarks and USD/CNY, data through November 5–6, 2026); E.SUN Bank (USD/TWD spot exchange rate, retrieved November 8, 2026); China Steel Corporation (December monthly pricing announcement, November 5, 2026); SteelWorld (mill pricing, distribution and raw material reporting, through November 7, 2026); Mysteel (through November 6, 2026; Tangshan billet through November 8, 2026); Lange Steel (quality and specialty steel weekly report, through November 6, 2026); Japan's Nikkan Tekko Shimbun (Mitsubishi Steel price increase, November 5, 2026); South Korea's SteelDaily (specialty steel bar distributor pricing, November 6, 2026).
This report is published by the Market Research Department of Double Steel Co., Ltd. It is intended for market research and procurement evaluation only and should not be used as the final basis for investment or direct purchasing decisions.